Project Overview
Three Brands, Three Market Positions, One Field Team
About the Company: A midsize dermatology company selling three brands with one national field team. The brands share a prescriber base. They do not share a market position.
Two products were fighting for share against direct competitors. The third, a specialty biologic, was losing ground and needed a better way forward. Fifty-five reps covered all three brands nationwide.
About the Partnership: The engagement grew in stages. An Opportunity Analysis came first, comparing the target list the field was using against a new one built with the company's brand strategy and updated data. The gap it surfaced made the case for piloting dynamic targeting with 12 reps. After six weeks, the pilot results made the case for a national rollout of ODAIA Field Intelligence.
One question framed the engagement: could dynamic, PowerScore-driven targeting move share and revenue across a multi-brand portfolio inside two quarters?
Results at a Glance: Throughout the 6-month analysis period, every brand in the portfolio had moved.
- 1,163 high-priority prescribers found sitting in low-priority segments
- Call volume up 29% across all three brands
- All-time-high market share on two of the three brands
- ~$3.33M in incremental Rx against the pre-ODAIA projected trend
The Challenge
Static Segments in a Market That Kept Moving
Prescribers move. An HCP who wrote nothing last quarter starts a patient this quarter. A reliable writer switches to a competitor. A physician changes offices and their patient mix changes with them. None of that shows up on a target list built over six months ago.
For this company, the problem compounded across three brands.
- Segment labels outlived the behavior behind them.
Priority segments were set against stagnant evaluation. A prescriber who moved into real opportunity kept their old segment until the next refresh cycle, so the call plan kept pointing elsewhere. - Three unique brand strategies, shared across one national sales team.
Fifty-five reps covered a portfolio where each product faced a different market. Two brands were growing share against competitors while the third was eroding, and the static list offered no way to see which brand had the strongest opportunity with a given HCP. - A declining brand had no early-warning signal.
The specialty biologic was losing ground. By the time that showed up in lagging Rx data, the HCPs driving the decline had already moved on.
The static list wasn't wrong when it was built. It just stopped describing the market within weeks of being published. It's a pattern seen across commercial teams, and one that's unpacked in Pharma's Guide to Dynamic Targeting.
The Solution
From Opportunity Analysis to Full Deployment
1.) Uncover opportunities
An Opportunity Analysis takes the customer's brand strategy, any available data, and builds an updated target list from it, then compares that list against the one the field is working today. The difference is the opportunity: HCPs who have changed since the last evaluation.
Why it matters? It quantifies the gap before anyone commits to a rollout. Once ODAIA is live, the comparison runs continuously, so the list never goes stale again, and field teams are always aware of any HCP movements. The table below identifies meaningful whitespace that was sitting in lower-priority segments.
Each of the identified prescribers were already in the territory. None required a different HCP universe or a new data build. Movement runs both directions, and the analysis caught both (examples below).
Protecting rep time from the second case matters as much as surfacing the first. PowerScores are produced by the Value Engine, which is explained in more depth on our platform overview page.
2.) Measure Activity
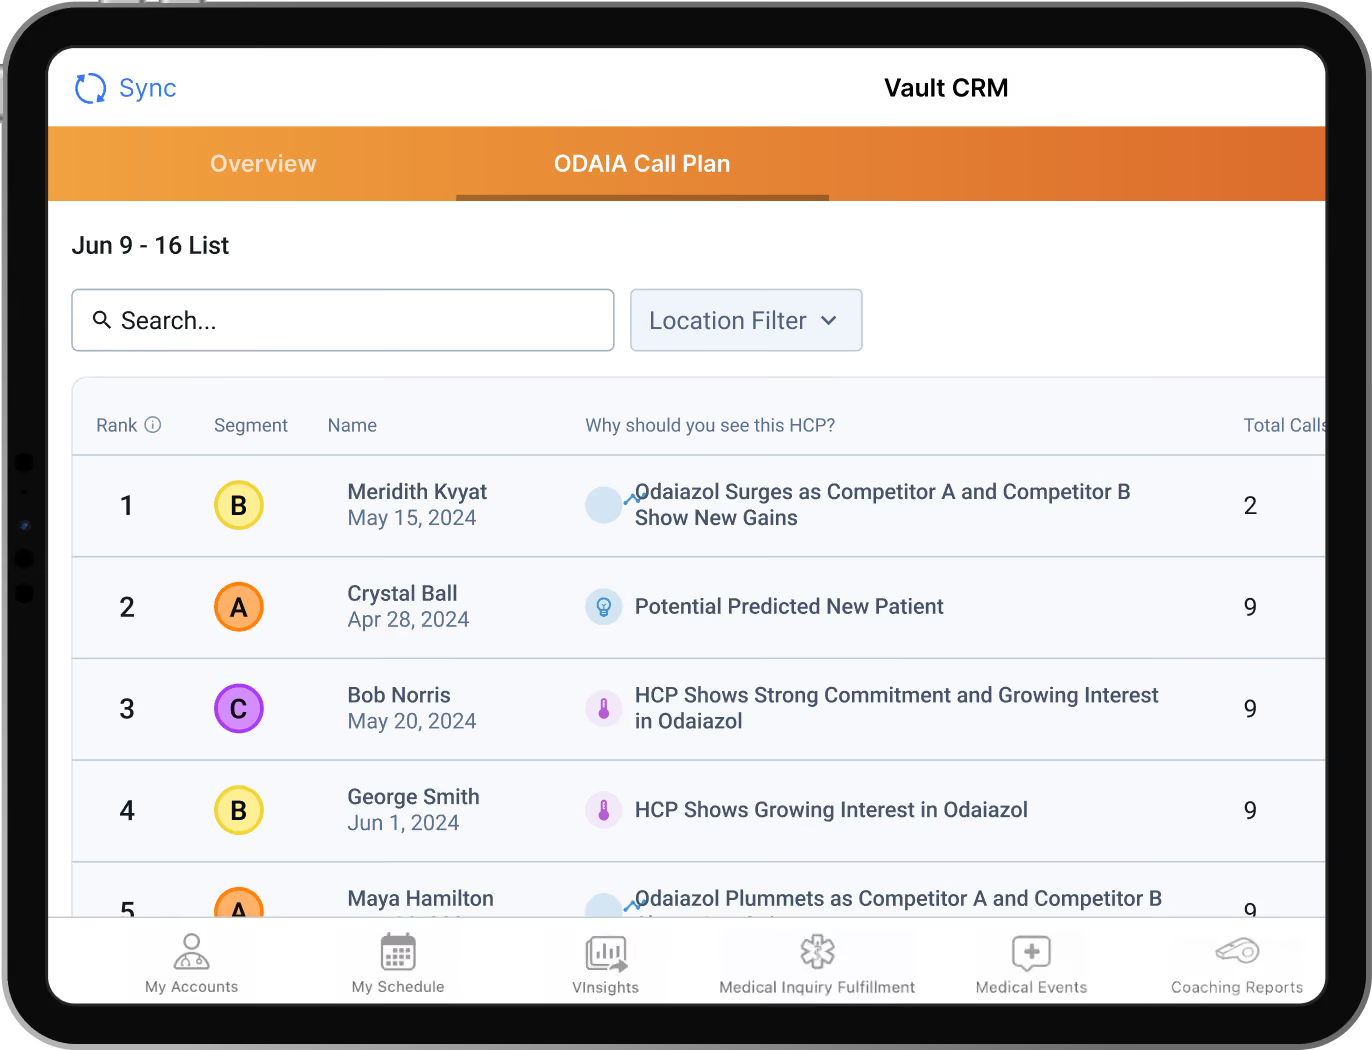
A six-week pilot with 12 reps validated the approach before wider deployment. Full launch followed, expanding to a national team of 55 active field reps. The measurement plan was built around three questions:
- Is the platform being adopted?
- Is targeting behavior actually changing?
- Is that behavior change converting into revenue?
Leading indicators the first two. Login sessions, HCP profile views, call adherence, and call volume all signal whether the field is working the plan.
Why it matters? Prescription data lags. Activity data does not, so the team could see whether the deployment was on track while there was still time to correct it.
Dynamic HCP scoring and weekly call lists put reps in the right places at the right time. The rest is follow-through, and that depends entirely on whether reps trust what they're being shown.
Activity metrics captured during the 6-month rollout to the National field team:
- 14,000+ login sessions across 55 field reps
- 62,000+ HCP profiles viewed
- 90% weekly active usage, sustained
- 69% call-list adherence
- 29% increase in call volume across brands
That trust problem is the one most deployments underestimate, and it's the subject of Rebuilding Sales Rep Trust: A Field Perspective on Dynamic Targeting.
3.) Evaluate Outcomes
Once lagging prescription data landed, actual performance was measured against the projected value for each product, calculated per brand and summed to the portfolio level.
Why it matters? Evaluating revenue impact per brand is what makes the number defensible. Portfolio lift that can't be decomposed by brand teams doesn't survive a finance review.
The Results
Measurable Lift, Brand by Brand
Each brand started in a different market position, so each result reads differently. Revenue was measured by comparing NRx, NBRx, and TRx dollarization against each brand's pre-ODAIA projected trend. Prescribing behavior was tracked separately, per product, to show where the gains came from.
One result goes beyond the numbers in the table. On Product 1, the behavioral microsegments didn't just rank prescribers, they predicted which groups would respond — Growers and Switch-Ins delivered the largest TRx gains of any segment. That's the difference between a priority list and a forecast. More on the thinking behind behavioral grouping in From Segments to Personal Journeys.
Key Takeaways
What Made it Work Across a Portfolio
This deployment tested something a single-brand rollout couldn't: whether one scoring system could coordinate three different commercial strategies through the same field team.
Each brand needs its own answer for the same prescriber.
An HCP can be low priority for one product and the best opportunity in the territory for another. A single static list can only hold one answer. Scoring every HCP per brand gave the field all three, in the same visit.
Growing and defending ran off the same system.
Two brands were chasing share. One was trying to hold it. Both came down to the same question: where is this prescriber's behavior heading, and how fast.
The score held up when it was tested.
HCPs the model moved from Low to High doubled their TRx share. The score called it before the prescribing did. Most targeting approaches can't offer that check at all.
Nothing was committed on faith.
An Opportunity Analysis sized the gap at 1,163 prescribers. A six-week pilot with 12 reps tested it. The national rollout followed, then six months of measurement proved it out brand by brand.